


Market Intelligence
Weekly Wool Market Commentary
Moses & Son is committed to providing our valued customers the most current information and data to empower your decision-making process. Discover our latest Australian wool market weekly update below, along with archived reports for your perusal and analysis.
2026-S21
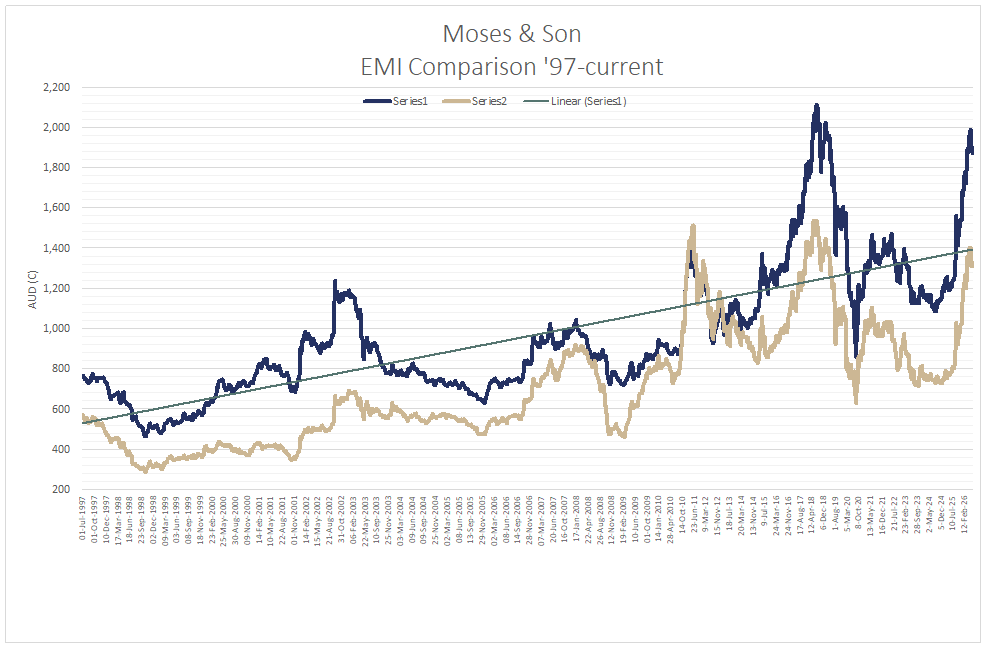
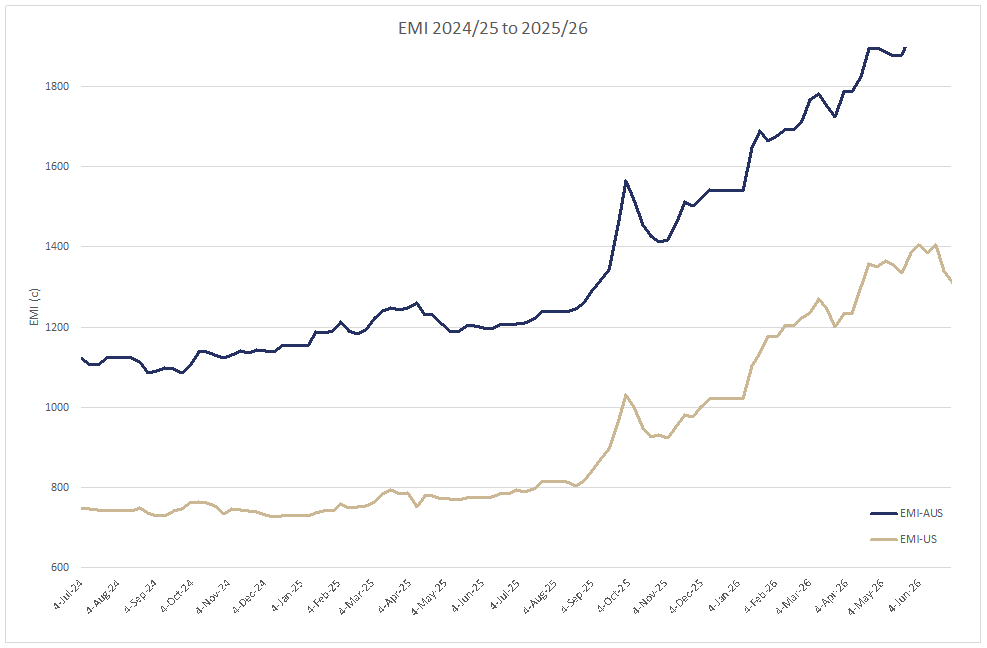
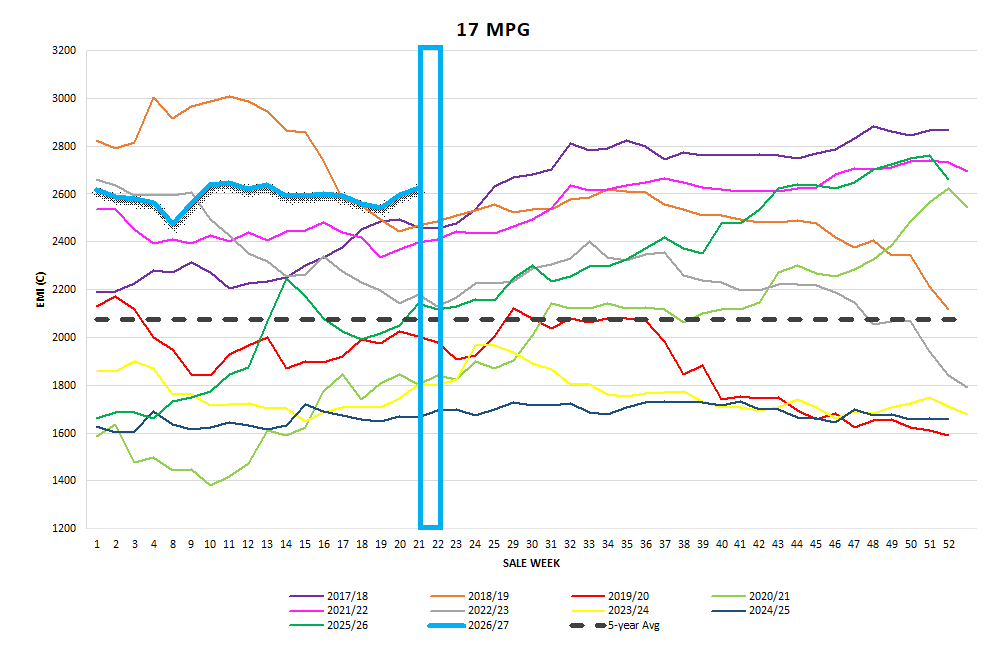
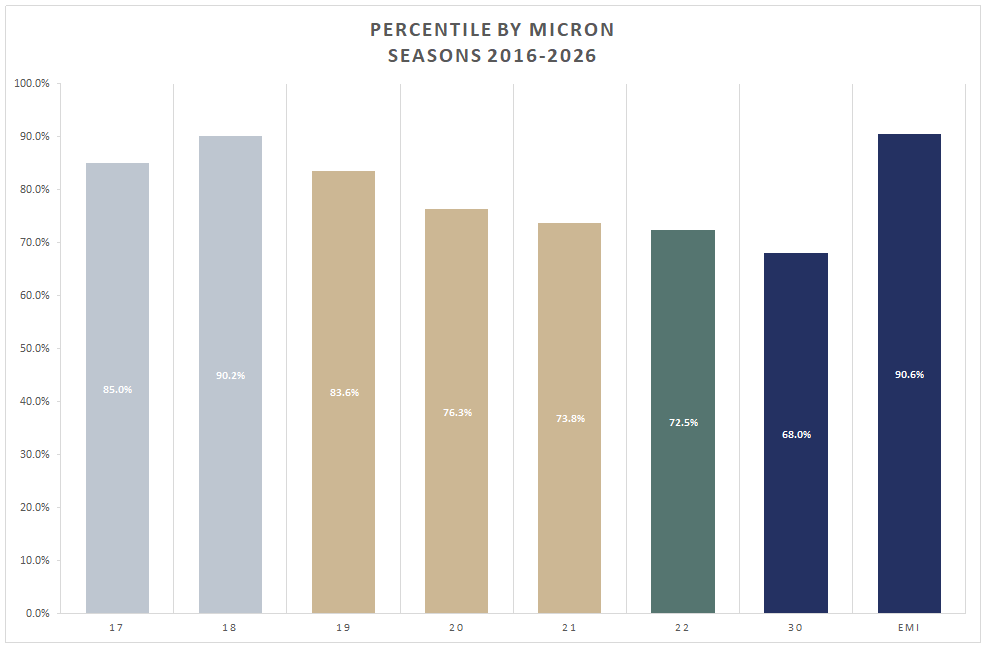
The AWEX EMI close on 1738c, up 16c at Wool Auction Sales in Australia this week. Despite the second week of the EMI recovering just 90.6% of the Australian stored offering was transacted to slightly more interested exporter cohort. Whilst the pass in rate in Melbourne and Fremantle fluctuated between 11% and 12%, Sydney kept their pass in rate at 4.7%. The depreciating AUD was the key driver in sellers favour with the AUD falling to 67.24 c which pushed the EMI down 15 USC. The EMI in AUD remains ~15% above the same time last year in AUD and ~19% above the EMI in USD terms as we enter the last month of sales before the Christmas sale recess. Bales offered through Auction year on year are down 72,714 bales (-12.9%) whilst the the value of wool traded YOY totals $939m up $95m (+11.3%).
Merino Fleece
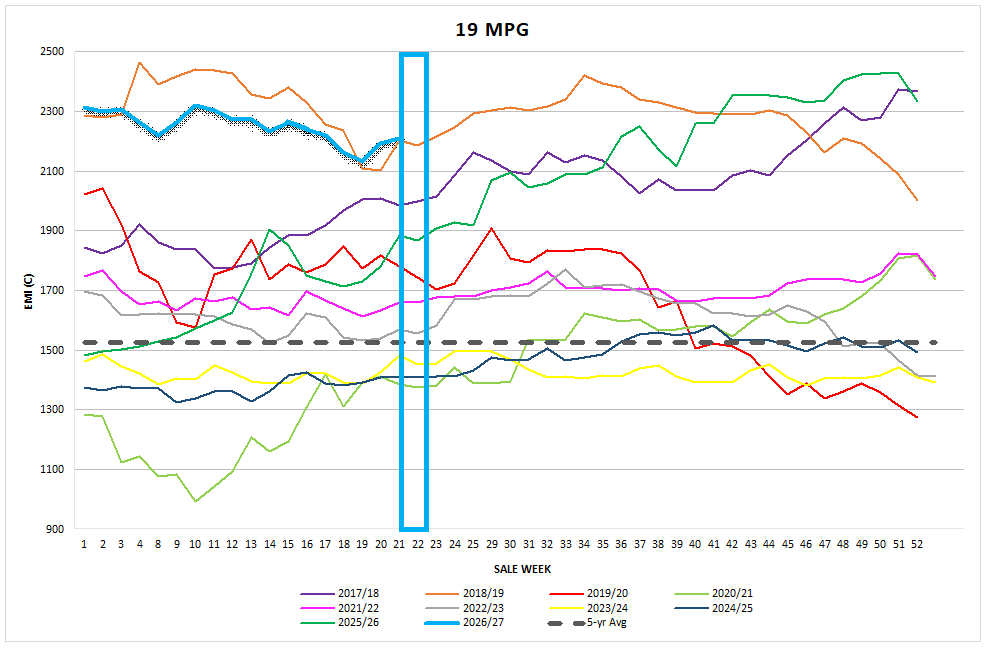
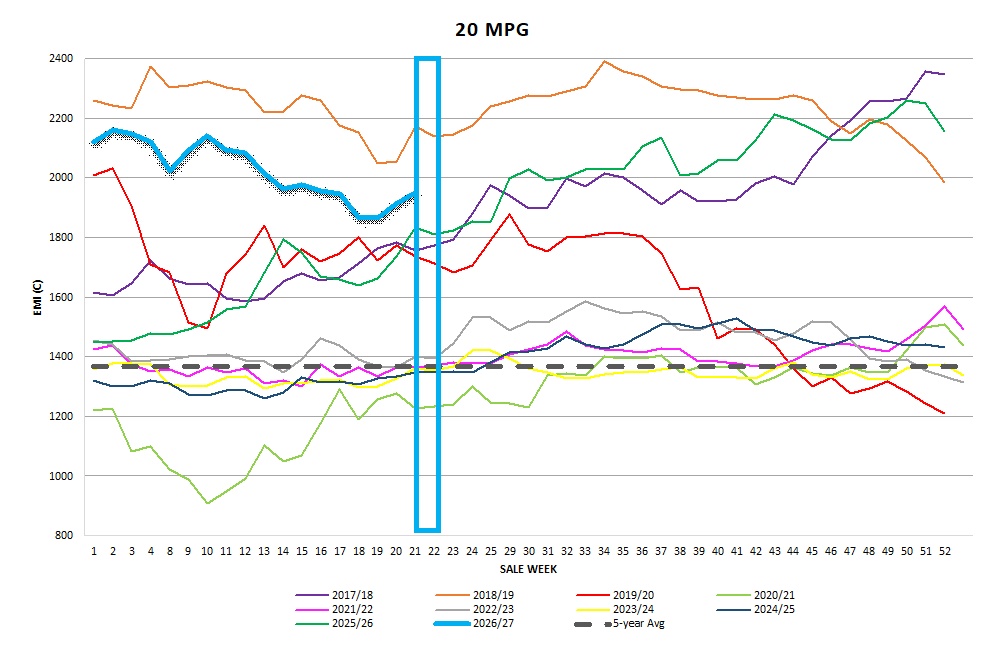
Merino Fleece: Demand remained strongest for better-style, well-measured merino fleece, particularly lots with low midpoint break and favourable additional measurement results. These superior prepared and specified lots attracted substantial price premiums with competition from European interests dominating. The good and average fleece types were dominated by the Large Chinese Top makers and Indent operators with the large Australian Based trading exporters in the mix but continually reporting ongoing difficult trading conditions.
Merino Skirtings
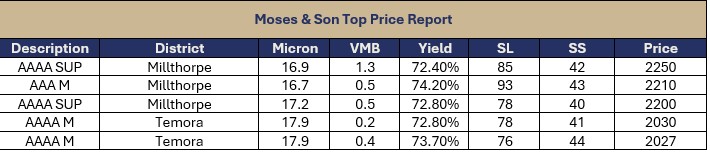
Merino Skirtings opened the week 10-20c dearer with slightly better competition on the best prepared, lower VM and superior specified lots pushing premiums at times to 50c over the market. As Wednesday's sale progressed prices stabilised around the previous day's levels. 74.2% of the skirtings sold went to the top 4 exporters with a healthy blend of Local Traders, Indent Operators and large Chinese Processors.
Merino Cardings
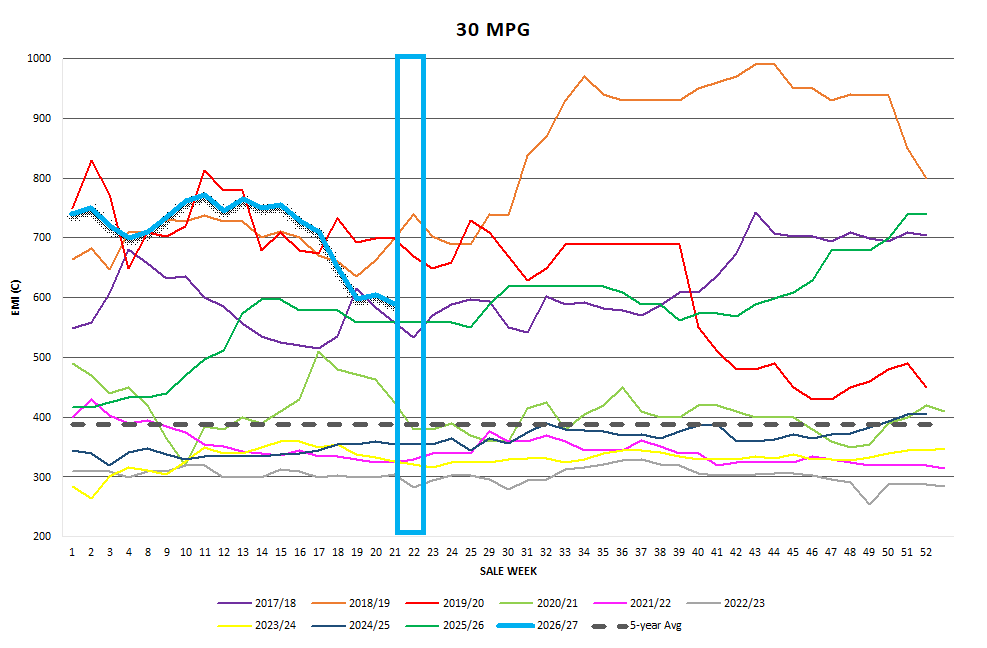
Merino Cardings posted variable results across the three selling centres. Sydney posted small incremental rises each day, mainly driven by spirited bidding on the fine Merino Locks pushing the MC to a weekly rise of 9c, whilst Melbourne's MC opened 12c weaker and was able to salvage a 2c rise on Wednesday to post a 10c loss for the week. Fremantle offering on Tuesday only with their MC posting a 1c loss for the week.
Crossbred Fleece
Crossbred Oddments
Crossbreds
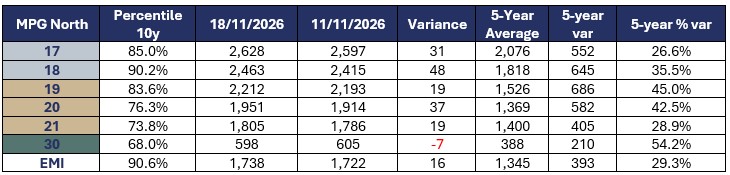
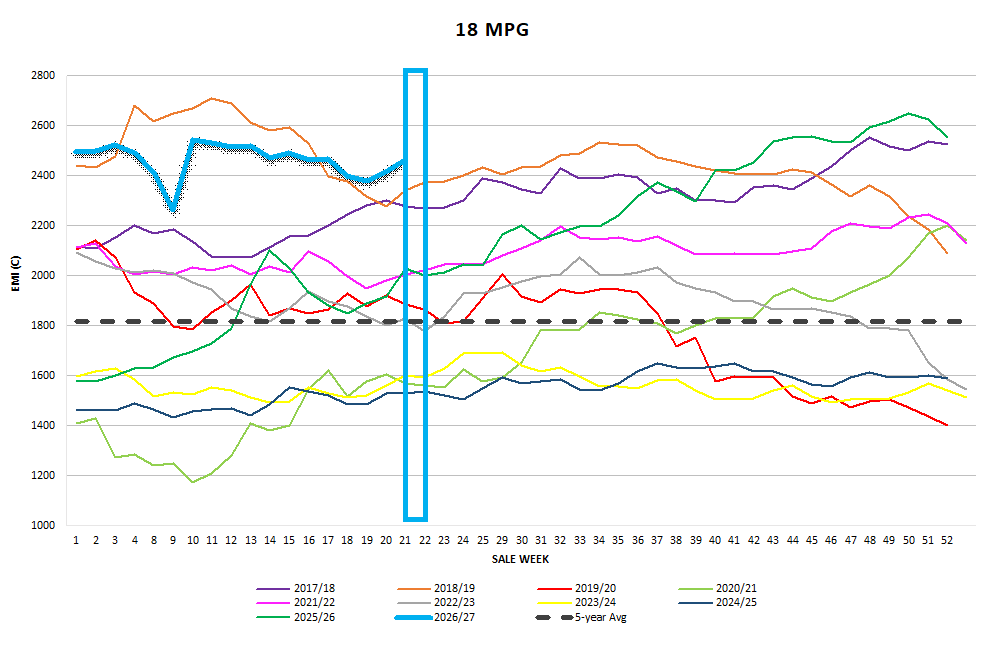
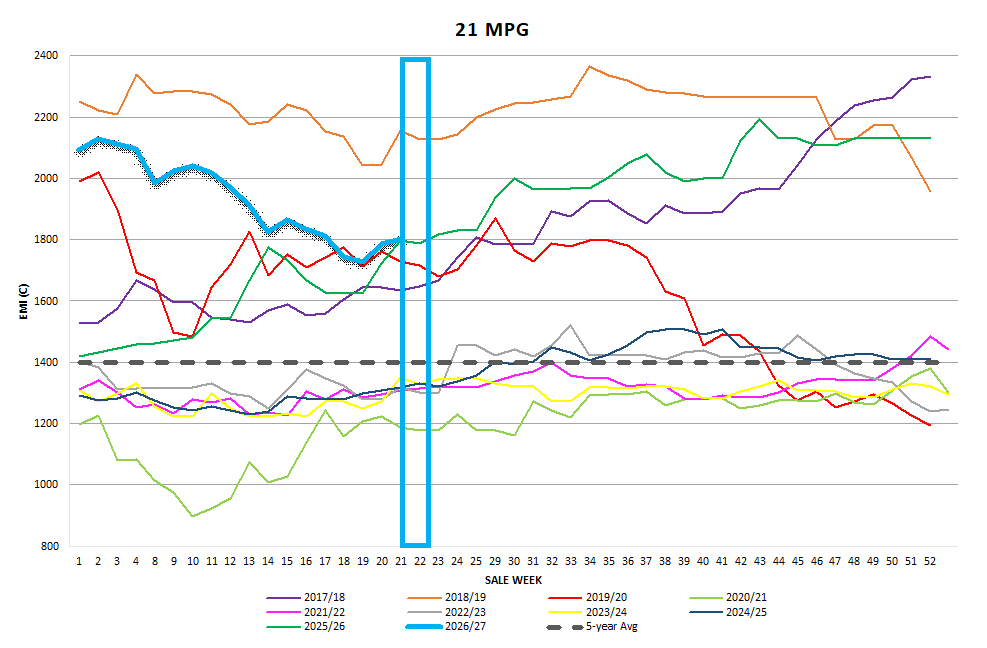
Crossbreds started the week with some new interest in the 26-27 micron best specified fleece with the northern 26MPG adding 19c. 28 micron and coarser continued to struggle with the increased offerings, posting slight falls in the Eastern state offerings.
Next Week
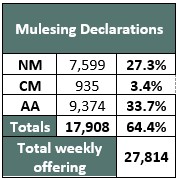
Next week’s national offering is forecast to rise to approximately 30,976 bales, including a designated Superfine Sale. With the Christmas recess approaching, restricted supply of preferred types may encourage further inventory replenishment by Chinese processors and the chase for the diminishing Superfine offerings will be in focus from the European exporters.
Whilst downstream demand is still uncertain, the overall supply tightness leading into the Christmas recess will place some pressure on purchasing for the shipping deadlines before the break. This market could break either way! ~ Marty Moses
Graphs
Market Commentary
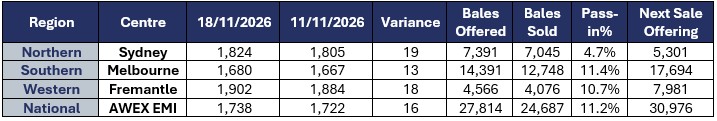
The EMI in AUD remains ~15% above the same time last year in AUD and ~19% above the EMI in USD terms as we enter the last month of sales before the Christmas sale recess. Bales offered through Auction year on year are down 72,714 bales (-12.9%) whilst the value of wool traded YOY totals $939m up $95m (+11.3%).